
Leading Indian Clothing Brands: Tradition, Innovation, and Market Leaders — What Brands Should Know
A buyer signs off a quotation in March, and the June inspection finds three shade variants of the same navy in one carton. That gap between…
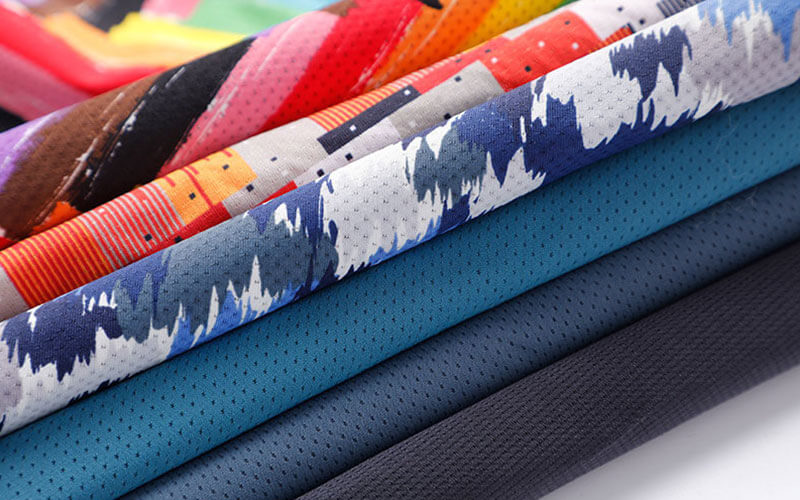
A buyer signs off a quotation in March, and the June inspection finds three shade variants of the same navy in one carton. That gap between a brand’s promise and a factory’s process is what most questions about Indian clothes companies are really about. India’s apparel sector runs from heritage weaving houses and ethnic-wear specialists to licensed global labels, value retailers, innerwear licensors and digital-first labels. What sets them apart is rarely size. It is where each one sits on the price ladder, how much of the fabric-to-garment chain it controls, and how tightly it locks fit and shade before a reorder is placed.
What sets India’s clothing companies apart: the short answer
The short answer: Indian clothes companies separate on three things — ownership of the fabric-to-garment chain, the market tier they price into, and how tightly they control fit and shade across repeat orders. Brands that own or partner on fabric and finishing tolerate reorders better; asset-light labels move faster on design but inherit batch risk.
Market segmentation: 26 Indian clothing brands grouped by aesthetic and specialty
Grouping Indian clothing companies by aesthetic and specialty tells a sourcing team more than ranking them by size, because two brands of similar scale can sit in completely different supply chains. The 26 names below are grouped by the buying behaviour each one serves, then tested against the variables in the next section.
Those variables explain most of what looks like brand personality from the outside. A vertically integrated mill group can hold a colour standard across seasons because it dyes its own yarn. A licensed label answers to an overseas owner for the fit block while sourcing from whichever partner can hit the price. A digital-first label may never touch fabric at all, working through converters who quietly own the technical decisions.
The tier a brand sells into sets its tolerance for cost, and that tolerance sets everything downstream. A value programme accepts a longer lead time to protect a thin unit margin; a premium programme pays more per piece rather than risk a shade break on the second order.
- Heritage textile and retail: Raymond, FabIndia
- Ethnic, occasion and designer: Manyavar, Biba, W for Woman, Soch, Ritu Kumar, Sabyasachi, Anita Dongre
- Formal and lifestyle, mostly licensed: Van Heusen, Allen Solly, Louis Philippe, Peter England, Park Avenue
- Value retail banners: Zudio, Max Fashion, Reliance Trends
- Innerwear and basics: Jockey (India licence), Dollar, Lux, Rupa
- Digital-first labels: Bewakoof, The Souled Store, WROGN, HRX, FabAlley
The commercial distinction is between brands that own a fit block and brands that license one. Ethnic and designer houses treat pattern and embellishment as house property, so a supplier receives a locked block and a strict finish standard. Licensed labels inherit the block from an overseas owner — the model operated by brand groups such as PVH Corp. — which shortens development but narrows the list of factories willing to build a block for a small run.
Comparison matrix: how the main brand groups differ on the variables buyers track
The variables a sourcing team tracks are not the ones a shopper sees. Four decide whether a programme is repeatable: who owns the fit block, who owns the fabric standard, what the price tier absorbs per piece, and where batch risk lands on a reorder.
| Brand group | Representative names | Specialty | Price tier | Fit and fabric standard | Where batch risk lands |
|---|---|---|---|---|---|
| Heritage textile and retail | Raymond, FabIndia | Suiting, ethnic and home textiles | Mid to upper | Group-owned across most of the chain | Processing mill; low at brand level |
| Ethnic and designer | Manyavar, Biba, Ritu Kumar | Ceremonial and festive, heavy surface work | Mid to high | Brand house, including embellishment | Dye-lot and embroidery variation |
| Formal and lifestyle | Van Heusen, Allen Solly, Peter England | Office and smart-casual shirting, trousers, knits | Mid | Brand owner controls the fit block | Moderate; spread across several vendors |
| Value retail banners | Zudio, Max Fashion, Reliance Trends | Fast private-label basics | Value | Retailer owns the specification | Low per style; volume absorbs variance |
| Innerwear and basics | Jockey (India licence), Dollar, Rupa | Daily-wear knitwear and multipacks | Value to mid | Brand or licence holder; partner processing | Shade and elastic recovery |
| Digital-first labels | Bewakoof, The Souled Store, WROGN | Print-led and fandom-driven casualwear | Value to mid | Brand owns design; partner owns construction | High per style; small runs leave no rework room |
Read the matrix as a risk map rather than a quality ranking. A supplier suited to a value banner will usually frustrate a designer house, and a workshop built for surface embellishment will misjudge knit waistband tolerances. For disclosure: Finetex Global is not an Indian company and does not appear in this comparison. The legal entity, Finetex Textile Co., Ltd., is a Shenzhen-based men’s knitwear OEM/ODM manufacturer, relevant here only where men’s knitwear sourcing criteria apply.
Strategic retail navigation: where India’s clothing brands actually sell online
Indian clothing reaches shoppers through three channels that behave differently enough to plan separately: marketplace aggregators, brand-owned direct sites, and social or messaging-led selling. Aggregators such as Myntra, Ajio, Nykaa Fashion and the large general marketplaces carry discovery; brand sites carry margin and the customer record; social channels carry the impulse purchase.
The trade-off is what each channel takes from you. On an aggregator, commission, fulfilment fees, packaging rules and returns policy all sit inside the retail price, and the customer relationship belongs to the platform. On a brand-owned site you set the price and own the data, but you fund traffic, photography and returns. That decides the specification: a platform listing typically wants single units, tight carton dimensions and label data the platform can validate, while a direct programme justifies multipacks and retail-ready packaging.
Decide the channel before the tech pack, because channel choice changes the size ratio, pack configuration and carton dimensions.
Industrial insights: the textile and finishing infrastructure behind Indian output
India’s advantage in apparel is depth rather than consolidation. Cotton spinning, knitting and weaving, processing and garment assembly all exist in-country at scale, and several clusters specialise enough that a buyer can source an entire programme inside one geography. The weakness is fragmentation: capability is spread across many small and mid-sized units, so the experience of one supplier says little about the next.
Knitwear and hosiery concentrate in Tamil Nadu and Punjab, man-made fabric processing concentrates in the west, and woven garment assembly is strong in the national capital region and the south. That depth supports reorders at speed, but it also means you rarely buy from one owner of the whole chain. Shade continuity, shrinkage tolerance and fabric weight must be written into the order, because spinning, knitting, dyeing and stitching may sit with four different companies.
The comparison points to hold suppliers to are ordinary ones: shade continuity across lots, shrinkage after wash, weight per square metre and colour fastness, all reported against a written specification.
What the 3-3-3 rule for clothes means for product planning
The 3-3-3 rule for clothes is a wardrobe heuristic rather than a regulation or a standard, and it circulates in more than one reading. The most common is a packing rule: three tops, three bottoms and three pairs of footwear, chosen to recombine into a workable set of outfits. A second reading is a buying filter, where a garment earns its place only if it pairs with three pieces you already own and is worn at least three times in the months after purchase.
Both readings describe the same commercial behaviour, which is what matters to a brand. The rule rewards items worn often and replaced often, which in most wardrobes means basics: underwear multipacks, plain T-shirts, polos, undershirts, loungewear. Novelty-heavy ranges look strong in a lookbook and weak in a repeat-purchase report, whereas a style that clears the three-times test will be reordered — and the reorder is where a supplier either protects your fit block or quietly breaks it.
Used as a merchandising filter, the rule tests an assortment before you extend it: styles that keep selling need shade and size consistency rather than new colours. Indicative MOQ for this type of programme starts around 300 pieces per style on stock fabric and rises with custom knit or dye lots, subject to the latest quotation.
Why no single Indian clothing website dominates the US market
There is no single largest Indian clothing website in the US, and the question usually comes from a diaspora shopping context rather than a market-share one. Indian apparel demand in the US is served through three routes: Indian-origin labels selling direct with international shipping, third-party sellers on large general marketplaces, and small specialists handling ethnic and occasion wear. The major Indian aggregators are built around domestic delivery, currency and returns, which is why their US-facing presence stays limited.
The barrier is not awareness alone. A garment sold in the US must carry fibre content, country of origin and care information, and those claims are regulated rather than optional — the FTC’s guidance on the Textile and Wool Acts and the rules at 16 CFR Part 303 set out what must appear, while care symbols on international labels are administered by GINETEX. Add duties, sizing conversion and returns cost, and the practical route to US scale runs through marketplace fulfilment or your own direct channel rather than an Indian retail site.
Treat the label file as part of product development rather than a printing afterthought.
Sourcing playbook: matching a partner to value, premium, sport and sustainable programmes
Match a partner’s economics to the programme you are actually running, and the shortlist sorts itself out. A value programme needs stock fabric, disciplined weight control and a supplier comfortable with multipacks. A premium programme needs custom dye lots, tighter tolerances and an approved physical sample held by both parties. A sport or compression programme needs the right machinery and performance testing. A sustainable programme needs certified fibre and traceable documents before the order is placed.
The usual failure is a mismatch of tier rather than of skill: asking a stock-fabric converter to hold a pima cotton shade across three lots is as unrealistic as asking a premium knitwear line to quote at a value price. Sport and compression add flatlock and cover-stitch capacity, elastic application, and performance claims a buyer should still verify through testing. Sustainable lines live on paperwork — fibre composition, chain-of-custody for bamboo, Lenzing modal, TENCEL and recycled polyester, and a current OEKO-TEX Standard 100 certificate naming the article produced.
At every tier, ask for the cost breakdown by fabric, labour, trim and packing. A single line-item price hides which of the four your supplier plans to trade against.
Cost and MOQ breakdown: fabric share, GSM and elastane trade-offs
In men’s knitwear, fabric is normally the largest single cost element in a piece, and the two levers a brand can pull are fabric weight and elastane content. Treat the usual planning band — roughly 45–60% of piece cost in fabric for knit basics — as indicative and subject to the latest quotation, because yarn choice, dyeing route and order volume move it. What matters is knowing which lever is being pulled, and what it does to the garment.
Weight and stretch are not free variables. Reducing grams per square metre lowers cost and can improve drape, but it affects opacity, handfeel and how a garment survives washing. Adding elastane improves recovery at a waistband or leg opening, but raises cost and adds a processing variable. Typical programmes run between 120 and 220 gsm across undershirts and T-shirts, while heavyweight fleece builds run far higher: 420 gsm French terry and 500 gsm brushed fleece where structure matters.
MOQ follows the fabric decision. Indicative structures start at 300–1,000 pieces per style in mixed sizes, with stock fabric allowing the lower end and a fully custom knit or dye lot typically starting near 1,000 pieces per colour, subject to the latest quotation.
Pre-production testing and QC gates to write into the contract
Write the gates into the order, because an AQL figure on its own does not tell you where a defect was allowed to pass. The sequence that protects a repeat programme is bulk fabric inspection before cutting, in-line inspection during the run, and final random inspection before the cartons are sealed. Skipping the first gate is what produces perfectly sewn garments in the wrong shade.
The fabric gate is specific: shade continuity across the lot, shrinkage after wash, weight per square metre and colour fastness. In-line inspection reported at roughly 30% and 70% of the run catches a drifting seam or an elastic application fault while material remains to correct it. Final inspection is ordinarily random sampling at AQL 2.5 with a photo report issued before packing and shipment. Underneath all of it sits one control: a version-controlled specification with an approved physical sample held by both parties.
Compliance documents belong in the same file. OEKO-TEX Standard 100 is renewed annually, and fibre composition and chain-of-custody records support bamboo, Lenzing modal, TENCEL and recycled polyester claims.
FAQ
What are the top 5 clothing brands in India?
There is no single authoritative ranking, because the ordering changes with the metric: revenue, store count, units sold or brand recall. Names that appear in most shortlists include Raymond and FabIndia among heritage and retail houses, Van Heusen and Allen Solly in licensed formal and lifestyle, Jockey’s India operation in innerwear, and Manyavar in ethnic wear. Treat any published list as a snapshot of one metric and check the basis before citing it.
Do Indian clothing brands manufacture in India or through overseas factories?
Mostly in India, though rarely end to end. Groups with mill or processing assets control more of the chain internally, while licensed and digital-first brands contract production and keep design and merchandising in house. Overseas sourcing is common for specific inputs: performance fabrics, technical knits, trims and programmes where the required machinery or certification sits elsewhere. Ask a potential partner which steps they control directly and which they subcontract.
How should a brand verify fibre and care label claims for the US market?
Start with the regulatory text rather than a supplier’s assurance. US labelling requirements for textile products cover fibre content, country of origin and care information, described in FTC guidance and codified at 16 CFR Part 303; care symbols used on international labels are administered by GINETEX. Build a label file per style that matches the bill of materials, then request the supporting test reports for fibre composition and colour fastness. A blend the mill cannot document is a claim you own.
Does a fabric certificate cover the finished garment?
No. A certificate applies to the article and scope it names, and OEKO-TEX Standard 100 certification is renewed annually, so a document from an earlier year or a different article does not transfer automatically. Check that the certificate names the material actually used, that the supplier named on it is the supplier in your order file, and that the certification year is current. Retailer onboarding usually adds a buyer-specific test programme.
Ask for a costed second opinion before you place the order. Finetex Global will read your specification, flag the cost lines that move the price and confirm what the fabric minimum per colour would be: contact Finetex Global. All figures are indicative and subject to the latest quotation.
Related resources
More factory-floor notes for brand owners

Sample Revision Limits: How to Control Underwear Development Cost and Calendar
A sample revision limit should control scope, not block necessary correction. The buyer and factory need to distinguish…
Read more →
Lab Dips and Strike-Offs for Underwear: Approval Steps That Prevent Delays
A lab dip approves a dyed textile shade; a strike-off approves printed artwork on the intended substrate. They…
Read more →
Color MOQ Planning: How to Share Fabric Across Multiple Underwear Styles
Color MOQ planning works best when a brand treats dyed fabric as a shared material platform rather than…
Read more →
Underwear Fabric Utilization: How Marker Efficiency Changes Unit Cost
Fabric utilization converts a fabric quotation into a garment cost. The calculation must account for pattern area, fabric…
Read more →
Open Costing for Men’s Underwear: Reading Fabric, Trim, Labor and Overhead Lines
An open-cost sheet is useful only when every line is tied to a measurable specification, a purchasing unit…
Read more →Global Apparel Sourcing Outlook 2026: Cotton, Freight and Supply-Chain Risk
A data-led 2026 apparel sourcing outlook on cotton balances, freight volatility, supplier diversification, lead time, compliance and practical…
Read more →Request a sample & pricing information
Send us your tech pack, target price or a reference sample — we reply with a quotation, a realistic lead time and a fabric recommendation within one working day.
- Free sampling plan & cost breakdown
- MOQ from 300 pcs per style
- Reply within 1 working day