Is China Still Competitive for Apparel in 2027? A Cost-Structure Breakdown
A 2027 China apparel cost-structure view using official wage data, with a qualitative look at fabric, energy, FX, automation and the transfer narrative.
Answer first: China remains a competitive place to manufacture many apparel programmes in 2027, but not because a single “cheap labour” number still decides the order. Competitiveness is a cost structure — labour, fabric, energy and the exchange rate — plus the things a wage series cannot show: fabric and trim availability, sample speed, quality systems, and the duty you actually pay at destination. Official Chinese wage data show manufacturing pay continuing to rise through 2025. They do not, by themselves, tell you whether a T-shirt or a brief will be cheaper or dearer than the same style made in another country. This article sets out a method for reading that structure, cites the official figures we could verify on 13 November 2026, and is explicit about what those figures do not cover.
It is not a forecast of Finetex prices, not a quotation, and not a prediction of 2027 inflation, freight or tariffs. For a line-by-line garment cost, use our apparel cost breakdown. For a country comparison that includes duty and lead time, see China versus Vietnam and China versus Bangladesh. For US duty layers on China-origin apparel, see our Section 301 guide, and re-check those rates with a licensed customs broker on the day you price.
The four cost blocks, and what official data can actually show
A factory FOB price, as explained in the cost-breakdown article, is built from fabric, CMT labour, trims, packing, and overhead plus margin. When buyers ask whether “China is still cheap,” they usually collapse all of that into labour. That is the wrong first move. The four blocks below are a way to unbundle the question. Only one of them — labour — has a current official nationwide wage series we could cite in this run, and even that series is not a garment piece rate.
Labour: official averages, not a sewing-minute rate
China’s National Bureau of Statistics (NBS) publishes average annual wages for persons employed in urban units. The 2025 release (published 15 May 2026) and the 2024 English release (dated 17 May 2025) report manufacturing as a whole, not a separate “garment sewing” rate.
| Series (NBS) | 2024 | 2025 | Nominal change, 2025 vs 2024 |
|---|---|---|---|
| Urban non-private units, manufacturing | 107,987 yuan | 113,594 yuan | +5.2% |
| Urban private units, manufacturing | 71,467 yuan | 76,055 yuan | +6.4% |
| Enterprises above designated size, production and manufacturing personnel | 78,561 yuan | 80,739 yuan | +2.8% (as stated for the 2025 figure) |
These figures are useful and limited in equal measure.
They are useful because they are official, dated and comparable year to year. They show that average manufacturing pay in urban units was higher in 2025 than in 2024, in both the non-private and private series. The private-unit manufacturing average remains well below the non-private figure, which is a reminder that “the China labour rate” is not one number.
They are limited because they are not apparel piece rates, not city-level sewing wages, and not the CMT line on a quotation. NBS is averaging across manufacturing industries, job types and regions. A knit brief made in one coastal city and an electronics assembly wage in another city can both sit inside “manufacturing.” The “production and manufacturing personnel” series for enterprises above designated size is closer to production roles, and NBS notes that this post category includes textile, knitting, dyeing and garment workers among many other production occupations — but it is still not a CMT rate you can multiply by a standard minute value. Social insurance, overtime rules, shift patterns and factory utilisation also sit outside the average wage.
Do not convert the table into a US-dollar labour cost per garment. That conversion would require an exchange rate, a minutes-per-garment assumption, and an efficiency assumption, all of which would be invented here. Use the NBS figures as a direction of travel for manufacturing pay, and use a quoted CMT line, with its operations listed, as the labour number that belongs on a costing sheet.
Fabric: usually the larger block, and the least visible in a wage table
For many knitted basics, fabric is the largest block of FOB, not CMT. Fabric cost is a cloth price, a consumption per piece and a wastage allowance, as set out in the cost-breakdown guide. China remains a major location for knitted fabric, dyeing and finishing as well as cut-and-sew. That matters because a programme that buys fabric and garments in one supply chain avoids a second international movement of cloth, a second lead time and a second quality hand-off.
We do not have, in this run, an official 2026–2027 price series for cotton yarn, knitted fabric or dyes that we can responsibly present as “the China fabric price.” Fibre markets move, and a custom colour has a dye-lot minimum that a stock fabric does not. Treat fabric competitiveness as a specification question: which fabric, at which width, in which colour, at which minimum, with which certificate. Ask for consumption and the cloth-price basis on the quote, and compare that block with a quote from another origin on the same specification. Our fabric selection guide and the fibre-certificate articles in this series are the place to take that question, not a single national average.
Energy: a real cost, without a figure we can invent
Dyeing, finishing, knitting and climate control in a sewing room all consume energy. Official wage data are not energy prices. In this run we did not extract a current official industrial electricity or steam tariff that could be applied to a garment. So this block stays qualitative: energy is part of factory overhead and of the mill’s fabric price; it moves when tariffs, fuel costs or efficiency change; and it should appear, if at all, as a stated assumption in a detailed quote, not as a round number in an article. Automation and process control, discussed below, are often aimed at this block as much as at sewing minutes.
The exchange rate: it re-prices a yuan cost into a dollar FOB
Most export apparel is quoted in US dollars. Wages, many domestic inputs and a large share of factory overhead are incurred in yuan. When the yuan strengthens against the dollar, the same yuan cost becomes a higher dollar FOB; when it weakens, the reverse occurs. The People’s Bank of China describes a daily USD/CNY fixing rate (central parity) formed with reference to prices enquired by the China Foreign Exchange Trade System (CFETS) from market makers before the market opens. That official fixing is the reference to watch. We did not extract a numeric fixing for 13 November 2026 from a clean official table in this run, so no rate is quoted here. Look up the current fixing on the PBOC or CFETS publication, date it, and apply it to your own yuan costs. Do not use a forecast. A one-week move in the fixing can change a dollar FOB by more than a small change in a sewing wage, which is why FX belongs in the cost structure even when it does not belong in a prediction.
Automation and what it does — and does not — change
Automation in apparel is uneven. Spreading, cutting, some finishing, warehouse handling and process control in dyeing are more automatable than a set-in sleeve or a narrow elastic at a pouch opening. A factory that invests in cutting or in dye-house control may reduce labour minutes and waste in those steps without turning a cut-and-sew garment into a “labour-free” product.
Two practical consequences follow, neither of which requires an invented productivity statistic:
- The labour share of FOB is not fixed. If fabric is half the price, a wage increase of a few percent in the CMT block changes the total much less than a fabric-price move of the same percentage. Official manufacturing wages can rise while a particular garment FOB still stands or falls on cloth.
- Capability can offset a wage gap. Consistent measurements, lower defect rates, shorter sample cycles and reliable packing reduce the cost of delays, returns and chargebacks. Those items do not appear in the NBS wage table. They appear in the landed cost and in the cost of a failed launch. Finetex’s published quality gates — incoming fabric inspection, in-line checks at 30% and 70%, final AQL 2.5, and a shipment check — and its published sampling and bulk lead times (sample 5–7 working days, size set 10–12 working days, bulk 15–45 days from deposit and approved pre-production sample) are part of that capability discussion, not a price.
Automation is therefore not a reason to ignore wages, and wages are not a reason to ignore the rest of the structure.
The “transfer” narrative, tested against a landed-cost file
The transfer narrative says that apparel leaves China because labour is no longer cheap, and that the next stop (often Vietnam, Bangladesh or another origin) is automatically the cheaper place to land a garment in 2027. A cost-structure view does not start with that conclusion.
A fair comparison, for one style, looks like this:
- Put both origins on the same specification: fabric, GSM, colour, trims, packing and quality gates.
- Break FOB into the five blocks in the cost-breakdown article, so you can see whether a gap is fabric, CMT, or something else.
- Add freight, duty and fees, as in our landed-cost sheet and six-input landed-cost method. For the United States, include the general HTS rate and any additional measures that apply on the day you price, confirmed by a licensed customs broker.
- Add the operational differences that are not in the duty file: minimum order quantity, sample time, fabric lead time, how many colours you can hold, and whether the fabric mill and the sewing plant sit in the same chain.
- Date every official input (wage series, HTS revision, FX fixing) so the comparison can be rebuilt later.
What this method usually reveals is that “China versus somewhere else” is not a single ranking. A basic cotton brief with a large, stable volume and a simple packing method may price differently from a short-run, multi-colour knit programme that needs rapid sampling and a certified fabric. Duty can outweigh a CMT gap; a fabric minimum can outweigh a duty gap. Our China–Vietnam and China–Bangladesh articles walk through those trade-offs without treating the lowest FOB as the right number.
The transfer narrative also tends to treat China as only a sewing location. For brands that develop fabric, colour and packaging with the same supplier, the relevant question is whether that package can be reproduced elsewhere at the same speed and documentation standard, not only whether a sewing minute costs less.
A conclusion you can use in a 2027 budget, without a false precision
As of the official figures checked on 13 November 2026, China is not a static low-wage sewing base. Urban manufacturing wages rose in 2025 on the NBS series cited above. That fact is real, and it belongs in any long-term view of CMT. It is not, however, a complete answer to whether China is still competitive for a given apparel programme in 2027.
Competitiveness still depends on fabric and trim supply, on energy and overheads that we have not pretended to price, on the dollar-yuan conversion you apply on the day you quote, on duty at destination, and on the ability to sample, control quality and pack to the channel. For many programmes those items still favour a China supply chain; for some volume basics, another origin may win on landed cost. The way to decide is a dated, like-for-like file, not a slogan about “leaving China” or “staying in China.”
If you are setting a 2027 budget, build the file for the actual styles, take the official wage series as background rather than as a piece rate, watch the official FX fixing, and have a broker confirm duty. We can contribute the FOB build-up, the lead time and the documents we can support, from the starting point on our about us page and the process in our clothing factory sourcing guide.
What is fact, what is advice and what is uncertain
Fact (checked 13 November 2026): the wage figures in the table come from NBS releases for 2024 and 2025. The existence of a daily USD/CNY official fixing is from PBOC’s published description of the CFETS process. Finetex lead times, MOQ and quality gates are as published on finetexglobal.com.
Advice: the four-block structure, the refusal to invent a piece rate or an energy tariff, and the five-step comparison are our practical method.
Uncertain: 2027 wages, fabric prices, energy tariffs, freight, FX and duty can all move. NBS manufacturing averages will not track any one factory’s CMT. This article is not a price forecast and not customs or investment advice.
Related reading
- China vs Vietnam for Apparel Manufacturing: Duty, Lead Time and Minimums
- China vs Bangladesh: When the Lowest FOB Is the Wrong Number
- Apparel Cost Breakdown: Fabric, CMT, Trims, Packing and Overhead
- Section 301 Tariffs on Chinese Apparel: HS Codes, Rates and Mitigation
Frequently asked questions
Are Chinese garment wages still rising?
Official NBS figures show that average annual manufacturing wages in urban units were higher in 2025 than in 2024: 113,594 yuan in urban non-private manufacturing and 76,055 yuan in urban private manufacturing. Those are manufacturing-wide averages, not garment piece rates.
Does a higher average wage mean China is no longer competitive?
No, not by itself. Fabric, duty, lead time, quality and the dollar-yuan conversion often move a landed cost more than a change in an average manufacturing wage. Compare origins on the same specification, with freight and duty included.
Why does this article not give a labour cost per T-shirt?
Because a responsible per-piece number needs a quoted CMT, a confirmed specification and a dated FX rate. Converting an NBS annual average into a garment cost would be an invented figure. We will not publish one.
What official FX rate should I use?
Use the current official USD/CNY fixing published through the People’s Bank of China / CFETS mechanism, and date it. Do not use a forecast from this article; none is given.
Should I move a programme out of China for 2027?
Only a like-for-like landed-cost file for that programme can answer. Duty, fabric minimums and sample speed can support either staying or splitting origins. We can help build the FOB and document side of that file; a licensed broker should confirm duty.
Sources
- NBS: Average Annual Wages of Persons Employed in Urban Units in 2024 (English, 17 May 2025)
- NBS: 2025年平均工资情况 (Chinese, 15 May 2026)
- People’s Bank of China: RMB exchange rates and related official pages
- USITC Harmonized Tariff Schedule
Build a 2027 cost file for a real style
Send us the garment, the fabric, the quantity and the destination. We will return an FOB build-up, a lead time and the documents we can support, with duty left for your licensed broker to confirm.
Request a quote or start from our clothing factory sourcing guide.
More factory-floor notes for brand owners
Selling Underwear in Germany: Textilkennzeichnung, LUCID and Packaging Law
German textile labelling, LUCID registration and packaging law for underwear brands after the PPWR and VerpackDG took effect…
Read more →
GSM to Ounce Converter and Fabric Weight Chart
Convert fabric weight between gsm and oz/yd² with the exact factor (1 oz/yd² = 33.906 g/m²), a T-shirt…
Read more →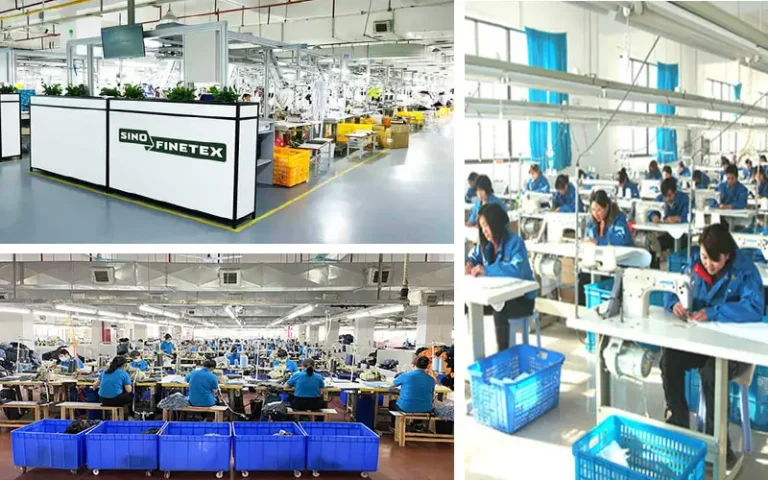
First-Output Check: The In-Line Inspection That Saves Bulk
What to check on the first garments off each line: measurements, seams, labels and print against the approved…
Read more →
A Fit Session Protocol for Knit Tops: 12 Wearers, 5 Measurements
A recommended fit session protocol for knit tops: recruit 12 wearers, take five measurements, run a movement checklist,…
Read more →
Corporate Uniform Programs: Tendering, Sizing and Reorders
How to run a corporate uniform program with a factory: tender documents, sizing a workforce, producing many sizes…
Read more →
Muscle Fit and Athletic Fit T-Shirts: Pattern Changes That Matter
How muscle fit and athletic fit T-shirts differ from a classic block: chest-to-waist drop, sleeve cap and bicep,…
Read more →Request a sample & pricing information
Send us your tech pack, target price or a reference sample — we reply with a quotation, a realistic lead time and a fabric recommendation within one working day.
- Free sampling plan & cost breakdown
- MOQ from 300 pcs per style
- Reply within 1 working day